
Living specialist launches debut €200m vehicle
in Green Street News | 13 Oct 2026 | 15:15 | London | by Amy Finch
“Alea targeting 10,000 flex and student beds in Portugal, Spain and Poland”, says co-founder Roey Shoef.
- What Alea has started fundraising for its debut strategy, aiming to reach up to €200m in equity
- Why Living-One fund will scale the living specialist’s student and flex platform to 10,000 units targeting Portugal, Spain and Poland
- What next Alea has already begun deploying the seed capital and is targeting an 18-month timeline to raise the fund.
Living specialist Alea has started fundraising for its debut strategy, aiming to reach up to €200m in equity, Green Street News can reveal.
Living-One fund aims to scale the Lisbon-headquartered student and flex platform in Portugal to Spain and Poland, targeting 10,000 units. The seed portfolio has around 2,500 units across Portugal, with 600 units under closing in Spain and the first units under closing in Poland.
Israeli investors Reality Group, Poalim Equity and Discount Capital have committed €50m as anchor investors to the value-add strategy. Reality and Poalim have also received a minority general partner stake as they see Alea’s long-term EU platform potential.
“Two factors allow us to stand strong in tougher times,” says co-founder Roey Shoef. “First, we control the entire value chain, so we don’t need to exit or dispose of assets immediately. Second, we develop for a high yield-on-cost.”
Alea has already begun deploying the seed capital and is targeting an 18-month timeline to raise the fund. The planning, underwriting and execution core team remains in Lisbon, but the firm aims to expand management and development staff in each market.
Green Street News caught up with Roey Shoef to discuss Alea’s geographical picks, flex living and platform sales.
Which investors are you targeting for your fund?
Our cornerstone investors are experienced Israeli investors. Reality Group has traditionally focused on Israeli investments and is now expanding elsewhere through investment in Israeli-related general partner stakes. Poalim Equity invests across asset classes, not just real estate. This is the first living-sector investment for both. They liked our track record and the fact that we are fully integrated.
As we move forward, we expect more global – and particularly European – investors who understand the value that we are bringing in our understanding of market dynamics. Another part of the appeal is our niche focus on a specific asset class.
Why have you chosen your target countries?
They all have sizeable student and working populations. Student housing provision rates are single-digit in Spain and Portugal, and in the very low double-digits in Poland. Those rates refer to student units, but that’s the long tail of a wider lack of accommodation, which supports the flex side of the business too.
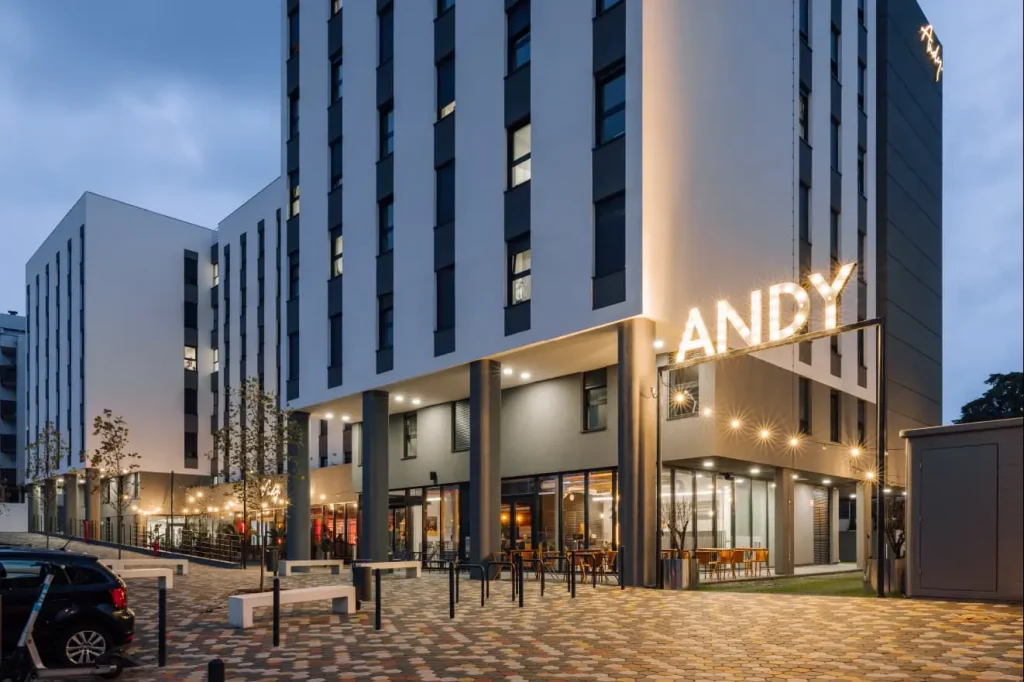
They are all supply constrained markets with institutional appetite – that’s the big thing for us. Spain and Portugal are more common when you talk to institutional players, but appetite for Poland is only rising.
They are also markets where our risk of execution is relatively moderate compared to others we examined. We believe that both our integrated model and underwriting discipline will benefit us there.
Does the nascency of the Polish market affect your approach? Why have institutions not targeted the market yet to the same level?
I can’t give you a real answer on why institutions haven’t entered as much, because I’m not one of them. I assume various variables. Currency is one of them.
But we love markets in this nascent phase. When we started working in Portugal, it was not as popular as it is today, and we started in secondary and tertiary locations. Our disposal there showed that as long as you control the process, building at high yield-on-cost to create very good assets, the liquidity is there. In less favourable market conditions, investors tend to flock towards premium locations but second- or third-tier locations are very appealing to us if those conditions are met.
“The number of significant student cities in Poland is amazing – several secondary cities there are on par with Lisbon in terms of student populations”
Poland is not quite a blue ocean, but it’s very close. The number of significant student cities is amazing – several secondary cities there are on par with Lisbon in terms of student populations. The local real estate market has goodprofessionals and an appetite for transaction, supporting lower execution risk and easier entry.
On the other hand, the Spanish market has grown increasingly competitive. How do you tackle that?
Spain is obviously the more mature one of the three and there are fantastic players working there. What we focus on is the resident experience from the get-go.
That applies to the way we develop our assets and grow our teams. Even if supply and demand become more balanced, the customer – whether the user or the parent – will decide based on the best overall experience versus price.
What’s the appeal of flex living to institutions?
Flexibility allows you to cater to different crowds in one asset, without the limitations of residential zoning. These projects are usually also of significant size, so the maths works. Much of the residential product in the markets we’re targeting is outdated, so a high-quality, professionally managed product is appealing to tenants.
You have a JV with King Street. Is this discretionary fund the next stage in your evolution?
We still pursue co-investments and we might still pursue some joint ventures. But it’s absolutely an evolution to be managing more discretionary capital, which allows us to have control and to expand into these new markets.
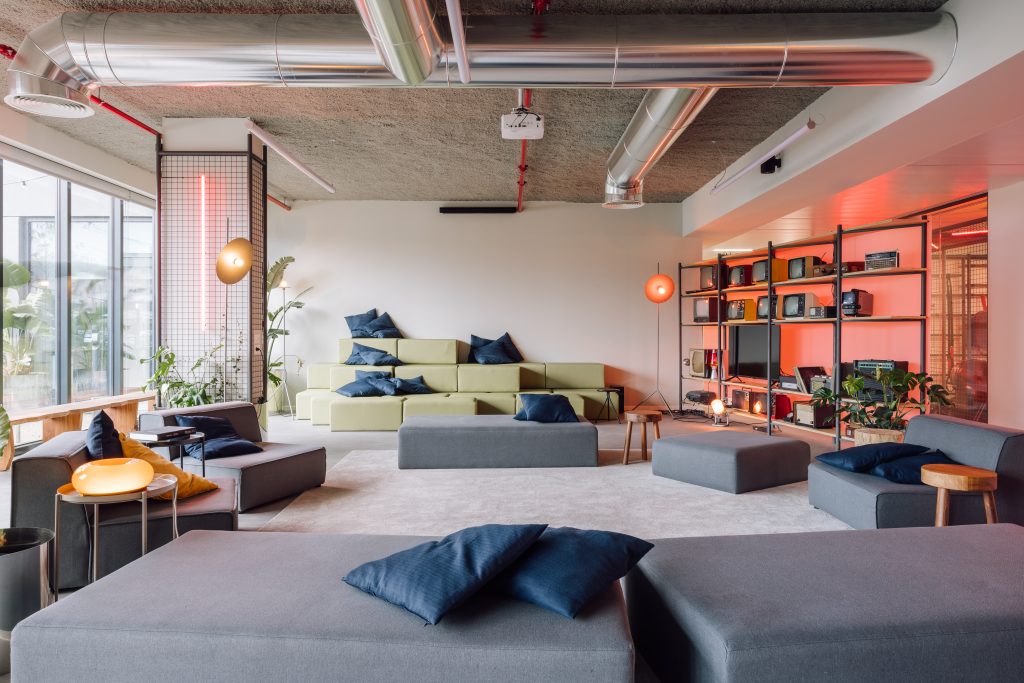
This is Living One and we hope to have Living Two and Living Three. Let’s see how we evolve from there.
How does a worsening macro picture affect you?
Macro turbulence affects everybody but two factors allow us to stand strong in tougher times. First, we control the entire value chain, so we don’t need to exit or dispose of assets immediately. Second, we develop for a high yield-on-cost.
“We have seen a platform premium in the last few years and we believe it will continue”
That was proven when we disposed of our assets in August 2023. Conditions were generally unfavourable, but when you have a significant spread above market, you can time your exit better.
Do you see the platform ultimately ending in a platform sale?
It could be the entire platform, or it could be split into two or three platforms. Having a platform in each of the jurisdictions allows for better liquidity.
We have seen a platform premium in the last few years and we believe it will continue. Various institutional players are creating very big platforms and buying quality sub-platforms. It’s a great value generator for them.
Special thanks to @Green Street News, and Amy Finch for the feature.